Help with Statistical Inference

  • Topic:
  • Thread starter trousmate
  • Start date
  • Tags Tags
    Statistical
3 replies · 2K views · last reply
trousmate
Messages
1
Reaction score
0
View attachment 3490

See image.

I have to present this on Monday and don't really know what I'm doing having missed a couple of lectures through illness. Any help or hints would be very much appreciated.

Thanks,
TM
 
Attachments
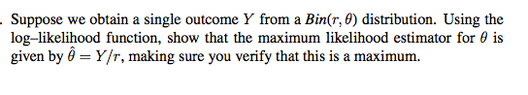
  • Printed text: Suppose we obtain a single outcome Y from a Bin(r, θ) distribution. Using the log-likelihood function, show that the maximum likelihood estimator for θ is given by θ̂ = Y/r, making sure you verify that this is a maximum.
    Screen Shot 2014-11-07 at 12.38.28.png
    6.8 KB · Views: 128
trousmate said:
https://www.physicsforums.com/attachments/3490

See image.

I have to present this on Monday and don't really know what I'm doing having missed a couple of lectures through illness. Any help or hints would be very much appreciated.

Thanks,
TM

Wellcome on MHB trousmate!...

If You have rsamples of a r.v. Y then the likelihood function is... $\displaystyle f(y_{1}, y_{2}, ..., y_{r} | p) = p^{\sum y_{i}}\ (1-p)^{r - \sum y_{i}}\ (1)$... so that... $\displaystyle \ln f= \sum_{i} y_{i}\ \ln p - (r - \sum_{i} y_{i} )\ \ln (1 - p) \implies\frac{d \ln f}{d p } = \frac{\sum_{i} y_{i}} {p} - \frac {(r -\sum_{i} y_{i})}{1 - p}\ (2)$... and imposing$\displaystyle \frac{d \ln f}{d p} = 0$ You arrive to write... $\displaystyle \overline {p}= \frac{\sum_{i} y_{i}}{r}\ (3)$Kind regards$\chi$ $\sigma$
 
trousmate said:
https://www.physicsforums.com/attachments/3490

See image.

I have to present this on Monday and don't really know what I'm doing having missed a couple of lectures through illness. Any help or hints would be very much appreciated.

Thanks,
TM

For this problem you have the likelihood:

$$L(\theta|Y) = b(Y,r,\theta)=\frac{r!}{Y!(r-Y)!}\theta^Y(1-\theta)^{r-Y}$$

Then the log-likelihood is:

$$LL(\theta|Y) =\log(r!) - \log(Y!) -\log((r-Y)!)+Y\log(\theta) +(r-Y)\log(1-\theta)$$

Then to find the value of $\theta$ that maximises the log-likelihood we take the partial derivative with respect to $\theta$ and equate that to zero:

$$\frac{\partial}{\partial \theta}LL(\theta|Y)=\frac{Y}{\theta}-\frac{r-Y}{1-\theta}
$$
So for the maximum (log-)likelihood estimator $\hat{\theta}$ we have:
$$\frac{Y}{\hat{\theta}}-\frac{r-Y}{1-\hat{\theta}}=0$$

which can be rearranged to give:$$\hat{\theta}(r-Y)=(1-\hat{\theta})Y$$ or $$\hat{\theta}=\frac{Y}{r}$$

and as you should be aware of; the maximum log-likelihood estimator for this sort of problem is also the maximum likelihood estimator.

.
 
chisigma said:
Wellcome on MHB trousmate!...

If You have rsamples of a r.v. Y then the likelihood function is... $\displaystyle f(y_{1}, y_{2}, ..., y_{r} | p) = p^{\sum y_{i}}\ (1-p)^{r - \sum y_{i}}\ (1)$... so that... $\displaystyle \ln f= \sum_{i} y_{i}\ \ln p - (r - \sum_{i} y_{i} )\ \ln (1 - p) \implies\frac{d \ln f}{d p } = \frac{\sum_{i} y_{i}} {p} - \frac {(r -\sum_{i} y_{i})}{1 - p}\ (2)$... and imposing$\displaystyle \frac{d \ln f}{d p} = 0$ You arrive to write... $\displaystyle \overline {p}= \frac{\sum_{i} y_{i}}{r}\ (3)$Kind regards$\chi$ $\sigma$

Very nice but this is the solution to the wrong problem, it just happens to have the same solution as the problem as asked, but it is still the wrong problem. The data is the number of successes from r trials not a vector of results.

.