EconometricAli
- 4
- 0
Hey everyone,
I'm doing an 3rd year economics course in university and I'm already running into difficulty trying to show proofs of the following:
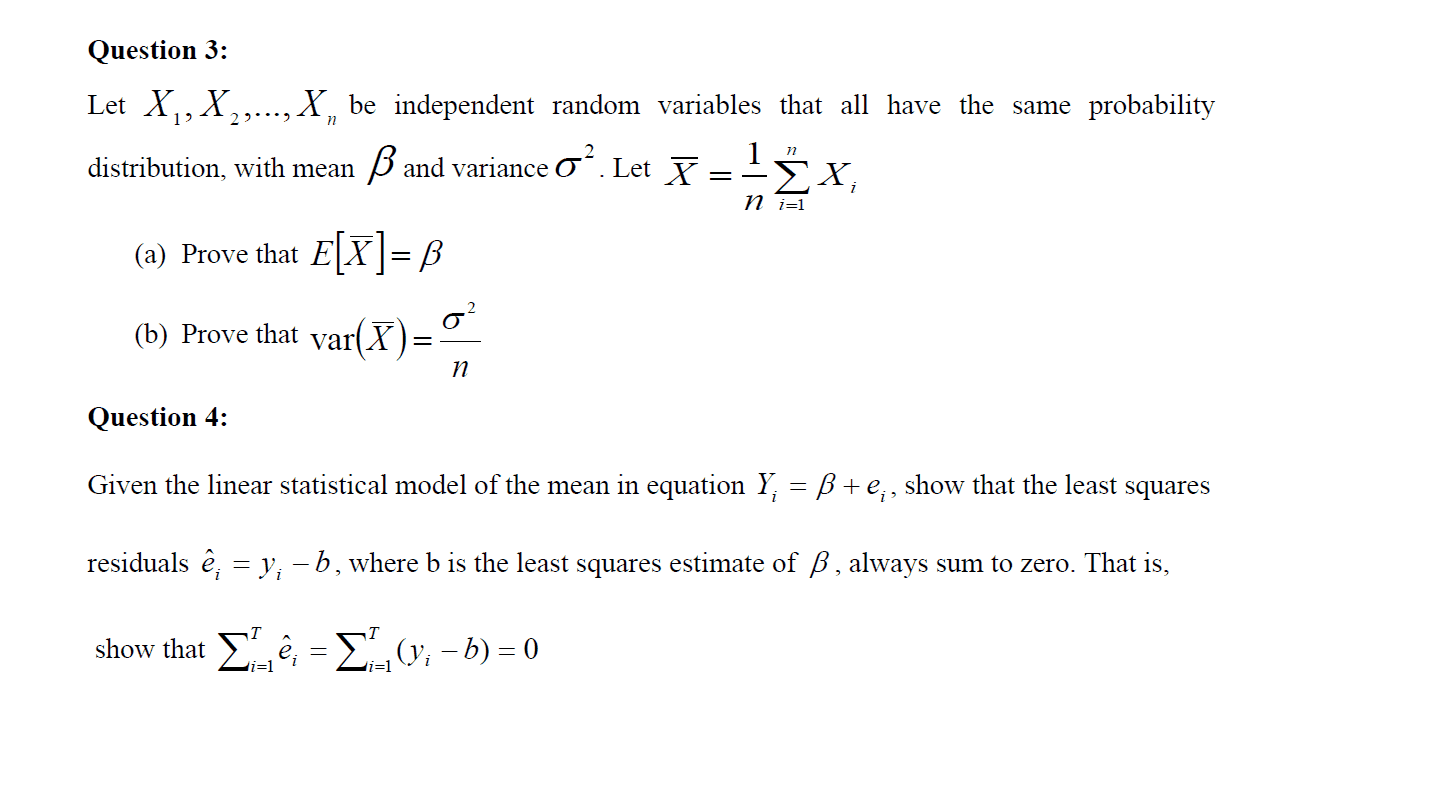
Now I certainly don't wish to ask for spoon feeding just some direction or source to where I can look up and read for the solution. My knowledge on these are still weak and the deadline is by the end of this Friday. I'm going to try the textbook tomorrow to see alternatives because I couldn't understand the lecture as well as I had hoped.
Thank you
I'm doing an 3rd year economics course in university and I'm already running into difficulty trying to show proofs of the following:
Now I certainly don't wish to ask for spoon feeding just some direction or source to where I can look up and read for the solution. My knowledge on these are still weak and the deadline is by the end of this Friday. I'm going to try the textbook tomorrow to see alternatives because I couldn't understand the lecture as well as I had hoped.
Thank you