Explaining E[(X−µ)³] calculation and variance formula

2 replies · 1K views · last reply
Kior
Messages
11
Reaction score
0
Member warned about posting without the template and with no effort
I am preparing for my math probability class next semester. There is question: Calculate E(x3µσ) Would anyone explain the solution in the picture a little bit to me?

1.Why is the step hold? Is there a formula or something that i can calculate E[X-µ]n?
2.Why is the fourth step hold? Where is the σ from and why variance σ2= E[X-µ]2?
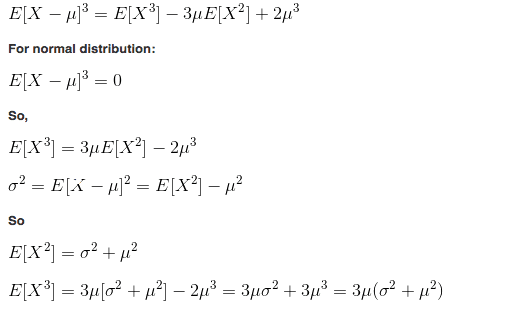
Handwritten-style math derivation: E[X−µ]³ = E[X³] − 3µE[X²] + 2µ³; for normal distribution E[X−µ]³ = 0; so E[X³] = 3µE[X²] − 2µ³; σ² = E[X−µ]² = E[X²] − µ²; so E[X²] = σ² + µ²; E[X³] = 3µ(σ² + µ²) − 2µ³ = 3µσ² + 3µ³ = 3µ(σ² + µ²).
 
If the distribution is continuous, then we have ## E[X^n]=\int X^n \rho(X) dX ##.
Then it can be proved that ## E[aX+c]=aE[X]+c ## which can be used to prove the first formula.
And variance is defined to be the expected value of the squared deviation from the mean, which means ## \sigma^2=E[(X-\mu)^2] ##.
 
Shyan said:
If the distribution is continuous, then we have ## E[X^n]=\int X^n \rho(X) dX ##.
Then it can be proved that ## E[aX+c]=aE[X]+c ## which can be used to prove the first formula.
And variance is defined to be the expected value of the squared deviation from the mean, which means ## \sigma^2=E[(X-\mu)^2] ##.

Note that ##\sigma^2 \equiv \text{Var}(X)## is given by
[tex]\begin{array}{cll} \text{Var}(X)& = E(X - \mu)^2 &\text{definition}\\<br /> & = E(X^2) - \mu^2 & \text{alternative formula}<br /> \end{array}[/tex]
Therefore, we have ##E(X^2) = \sigma^2 + \mu^2##.

To get the "alternative formula", just expand out ##(X - \mu)^2## and then take expectations.