Petr Rygr
- 1
- 0
Hello, could anyone please explain me some logic or derivation behind the approximation:
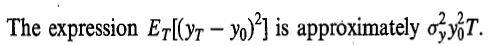
Found it in the Hull Derivatives book without further explanation. Thanks for help
Found it in the Hull Derivatives book without further explanation. Thanks for help