Break a Stick Example: Random Variables

1 reply · 2K views · last reply
ashah99
Messages
55
Reaction score
2
Homework Statement
Provided below in the comments
Relevant Equations
f(x,y) = f(y|x)f(x)
Law of iterated expectation: E[ Y ] = E( E(Y|X) )
Hello, I would like to confirm my answers to the following random variables question. Would anyone be willing to provide feedback and see if I'm on the right track? Thank you in advance.
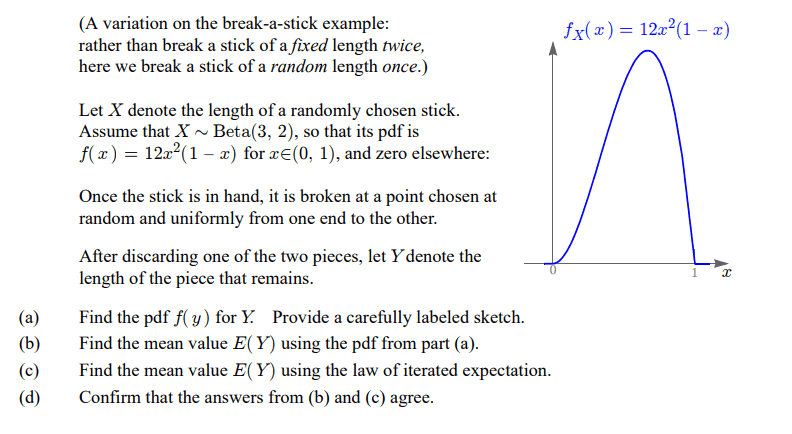
Problem statement on a stick-breaking random variable: text defining X ~ Beta(3, 2) with pdf f(x) = 12x^2(1 - x) on (0, 1), parts (a) to (d), and a blue plot of f_X(x) = 12x^2(1 - x) over 0 to 1.

My attempt:

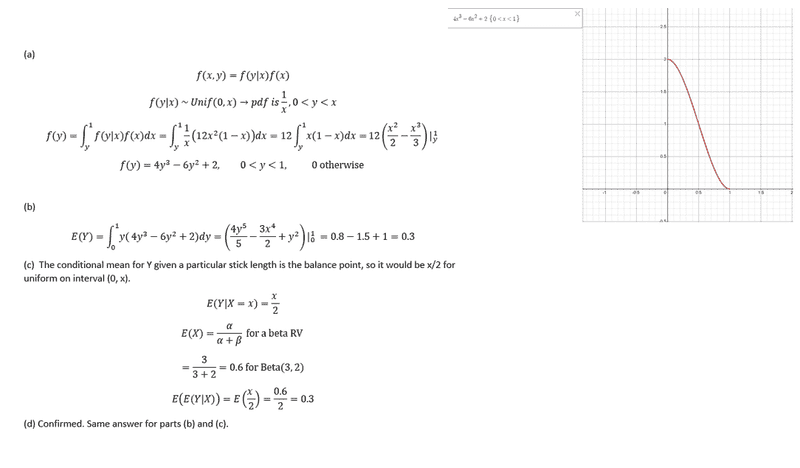
Handwritten-style worked solution on a math page: marginal density f(y) = 4y^3 - 6y^2 + 2 on 0 < y < 1, expected value E(Y) = 0.3, conditional mean E(Y|X=x) = x/2, and E(X) = 0.6 for Beta(3,2). Beside it, a plot of y against x with the curve 4y^3 - 6y^2 + 2 on 0 to 1.
 
You have not explained your choice of integration limits in (a), and I think the set-up of the integral is wrong.
One usually approaches problems like this by calculating a formula for the cumulative probability function ##F_Y(y) = Prob(Y\leq y)##, and then calculating the PDF as ##f_Y(y) = \frac d{dy} f_Y(y)##. Only in very simple cases can you skip these steps and go directly to the PDF.
The formula for ##F_Y(y)## will be a double integral over ##x\in(0,1)## and ##u\in[0,\min(x,y)]##. To start, draw a diagram of the integration region on an x-u plane. You will see that the region has a trapezium shape, so you will need to break the inner integral into two parts.